Home Loan
For Women
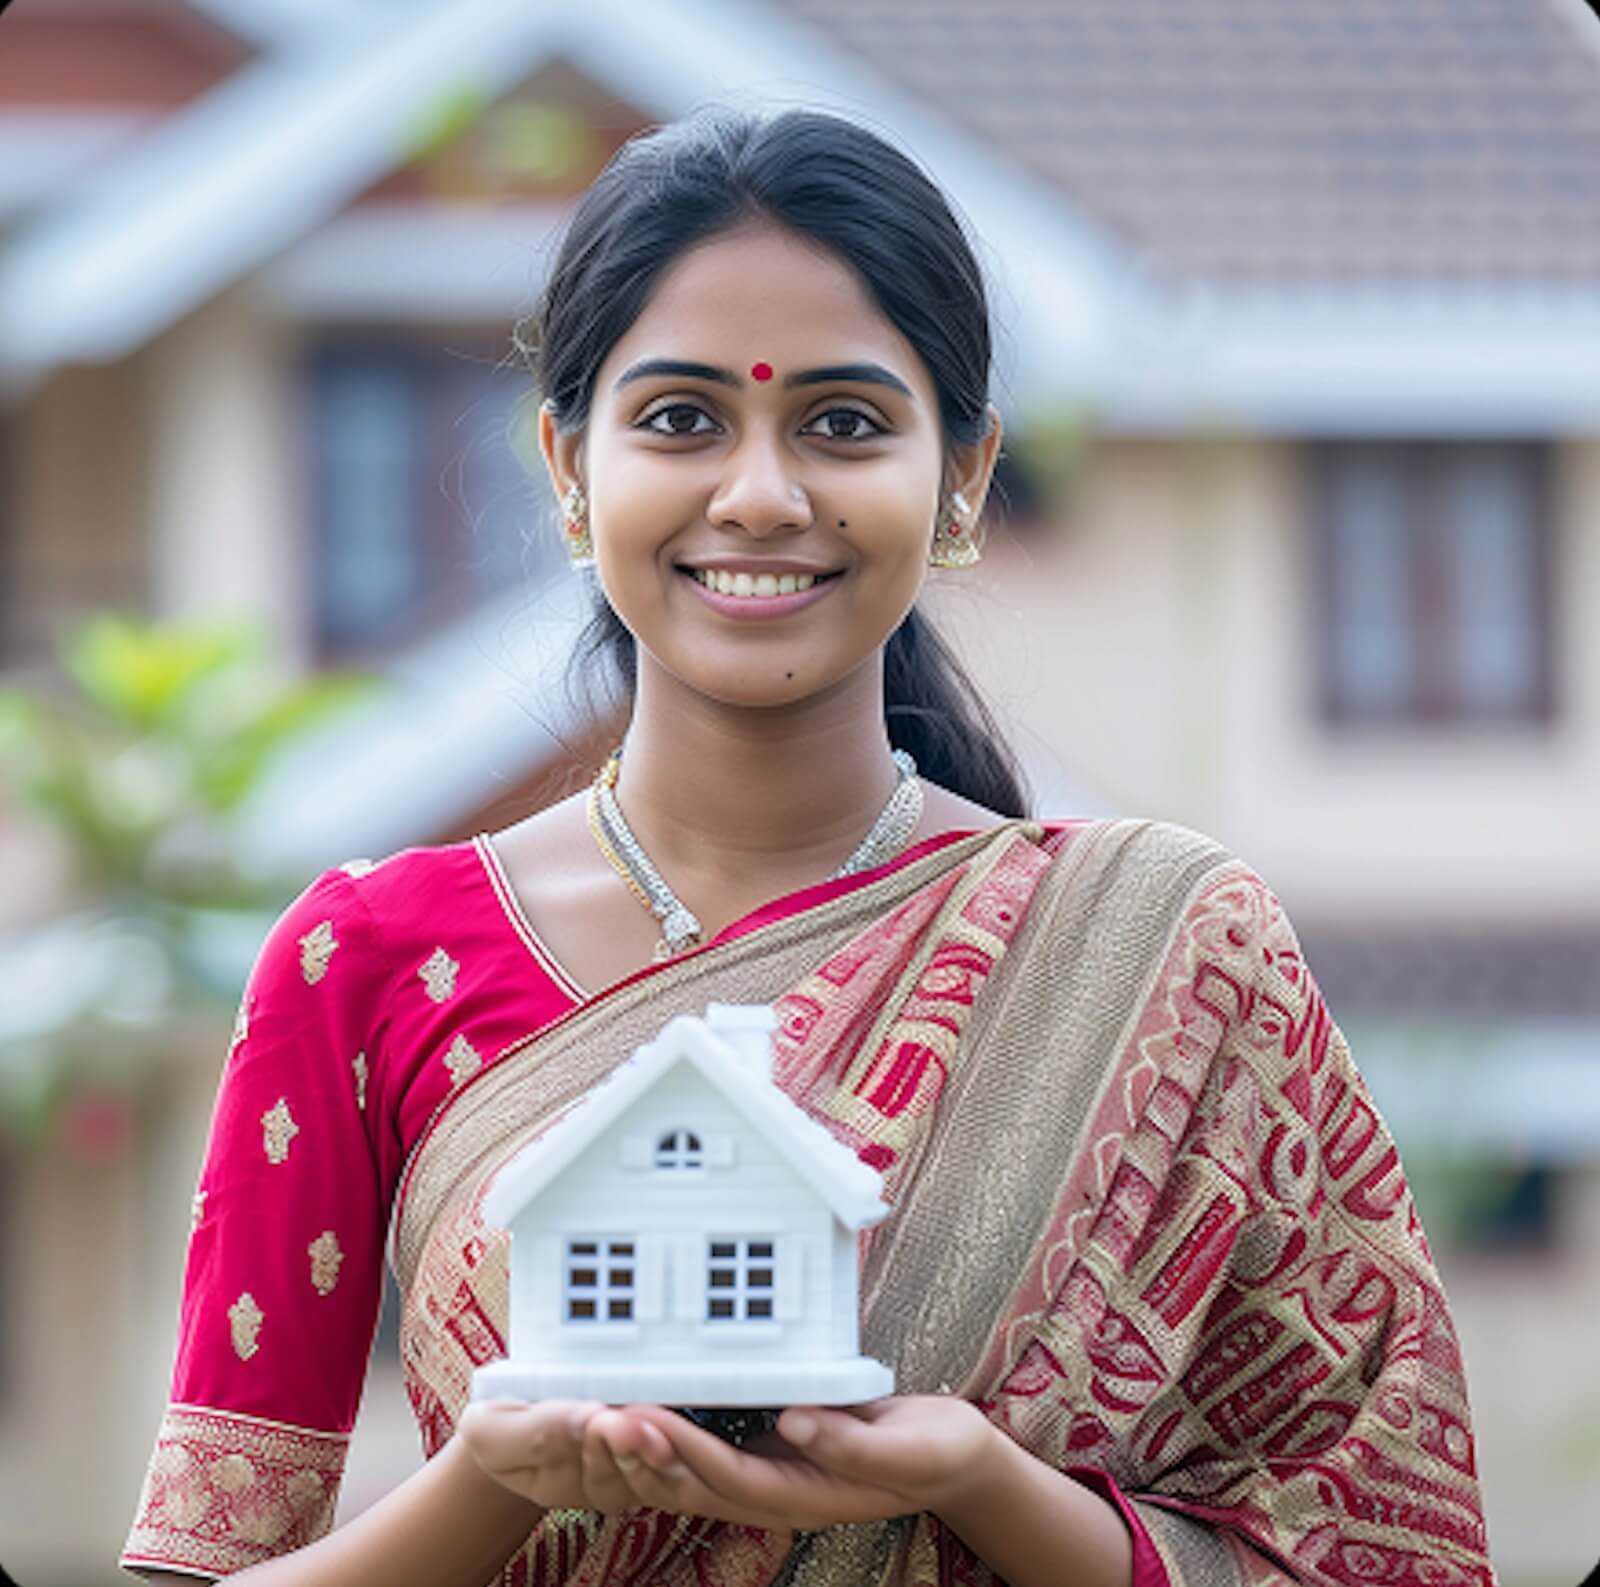
A lot of women want to buy a house on their own or with family members. For some, the goal is property ownership in their own name. For others, the goal is better financial planning and long-term security. When a woman owns or co-owns the property, banks provide her with particular benefits. These benefits may include lower interest rates, reduced stamp duty in some states, and improved eligibility in joint applications. A home loan for female applicants becomes easier to understand when these benefits are explained clearly. Our advisor at BASIC Home Loan reviews your profile and explains which benefits actually apply in your case instead of relying on assumptions.
What a Home Loan for Women Actually Means
A housing loan for women is a home loan where the main borrower or co-owner is a woman. Due to policy frameworks and risk assessment methodologies, lenders generally give female borrowers better terms.
A housing loan for women can be used to buy a home, build one, renovate an existing one, or transfer the balance, based on the borrower's needs. Whatever the case, involving an advisor can ensure your home loan application is hassle-free. And this is where BASIC Home Loan comes into the picture.
Initiate your home loan application process today!

Home Loan: Who is it For?
A housing loan for women is a home loan where the main borrower or co-owner is a woman.

Typical Home Loan Amount Range
Home loan amounts for women generally start from ₹10 lakh and can extend up to ₹16 crore, depending on income, repayment capacity, and property value.

Typical Home Loan Tenure Range
Home loan repayment tenures usually range between 5 years and 30 years, depending on borrower eligibility, age, repayment capacity, and lender policy.

Starting Home Loan Interest Rates
Home loan interest rates for women currently start from around 7.15% per annum with some lenders and may vary based on credit profile, income, loan amount, property details, and lender policies. Some lenders may also offer interest-rate concessions to eligible women borrowers
BASIC Home Loan: How Our Advisors Help Women Borrowers
Women borrowers often feel confused while dealing with multiple banks and lenders. Each lender follows different rules, timelines, and documentation requirements, which makes the process feel complex. Our advisor supports women borrowers at every stage of the home loan process.


Public Sector Bank
Stable and policy linked
Process driven
Selective
Moderate
Limited
Private Bank
Market responsive
Relationship-driven
Moderate
Faster
Available
Public Sector Bank
Profile-based
Flexible
Strong
Fast
Case-specific
We help female borrowers to get a hassle-free experience in their home loan journey. Our advisors bring clarity through realistic guidance to make the process smooth.
INTEREST RATES
Home Loan Interest Rates and Charges Comparison
| Bank Name | Interest Rate | Processing Fee | Loan Amount and Tenure |
|---|---|---|---|
 9.5% | 5 Years | ₹42,004 | Loan amount as per bank assessment. Tenure up to 30 years |
 HDFC Bank | 7.25% p.a. to 10.50% p.a. | 0.35% of loan amount (Min: ₹3,000 + GST, Max: ₹12,000 + GST) | Loan amount as per bank assessment. Tenure up to 30 years |
 PNB Housing | 7.25% p.a. to 10.50% p.a. | 0.35% of loan amount (Min: ₹3,000 + GST, Max: ₹12,000 + GST) | Loan amount as per bank assessment. Tenure up to 30 years |
 Federal Bank | 7.25% p.a. to 10.50% p.a. | 0.35% of loan amount (Min: ₹3,000 + GST, Max: ₹12,000 + GST) | Loan amount as per bank assessment. Tenure up to 30 years |
| SBI Bank | 7.25% p.a. to 10.50% p.a. | 0.35% of loan amount (Min: ₹3,000 + GST, Max: ₹12,000 + GST) | Loan amount as per bank assessment. Tenure up to 30 years |
A home loan interest rate for women may vary across banks and lenders. A woman's home loan interest rate may also differ based on individual financial profiles even within the same bank. Our advisor compares lender offers and explains how interest rates affect long-term repayment planning.
COMMON BENEFITS
Home Loan Benefits for Women
Women borrowers often receive certain advantages while applying for a home loan. These advantages may vary across banks and states, yet some common benefits usually apply in many cases. Key home loan benefits for women usually include:
 Our advisor explains how these benefits apply based on your income profile, property type, and lender selection.
Home Loan Criteria For Women
HOME LOAN SCHEME FOR LADIES
Home Loan Scheme for Female Borrowers
Lower interest rates compared to regular home loans
Flexible repayment options based on income patterns
Simplified documentation requirements
Higher eligibility in joint applications
Additional benefits depending on lender policies
Tell us about your requirements
DOCUMENTATION
Documents Required
Salaried Individuals
Identity proof such as Aadhaar card, PAN card, or passport
Address proof such as utility bills or official ID documents
Income proof, such as salary slips or tax returns
Bank statements for recent months
Property-related documents such as an agreement or allotment letter
Home Loan Interest Rate for Women
Credit Score and Repayment History
Your credit score and past loan repayment behavior significantly influence the interest rate offered.
Income Stability and Employment Type
Regular income from stable employment helps secure better interest rates.
Property Value and Location
The value and location of the property impact the loan terms and interest rates.
Existing Financial Commitments
Current loans and financial obligations are considered when determining rates.
SOLUTIONS
Common Challenges and How We Solve Them
Income Variability
Due to employment or business nature, income may vary across different periods.
Property Approval Issues
Legal verification and property approval can sometimes be challenging.
Joint Ownership Complexities
Co-applicant related complexities may arise during the application process.
Lender Selection
Difficulty in choosing the right lender that matches your profile.
Limited Credit History
Low credit score or insufficient credit history can affect approval chances.