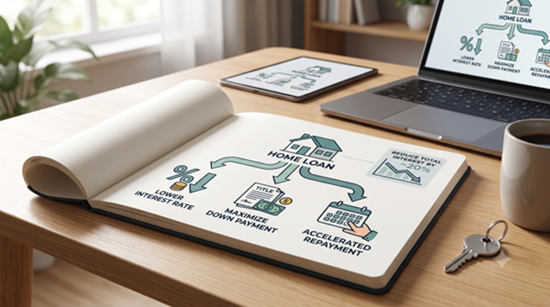
Most people sign their home loan papers, set up an EMI auto-debit, and forget about it for the next 15 or 20 years. That’s the default path, and it’s usually the most expensive one. With a bit of planning around tenure, down payment, and repayment, you can realistically cut your total interest outgo by a meaningful chunk, sometimes close to 20%, without changing your lender or your loan amount drastically.
This blog walks through practical ways to reduce home loan interest legally, using tactics that actually work.
Ways to Reduce Home Loan Interest Legally
1. Start with a Tenure You Can Actually Afford
A lot of borrowers default to the longest tenure offered, since it lowers the EMI. Fair enough, it eases monthly pressure. But a longer tenure means paying interest for longer, and that adds up fast. If your income can comfortably support a slightly higher EMI, choosing a shorter tenure from the start cuts your total interest by a large margin. Even trimming five years off a 20-year loan can make a real dent.
2. Make a Higher Down Payment
The less you borrow, the less interest you pay, plainly put. Most lenders let you borrow up to 80-90% of the property value, so many buyers put down the minimum. But if your savings allow it, pushing your down payment to 25-30% instead of the standard 10-20% reduces your principal right from day one. A smaller principal means a smaller interest bill across the entire tenure, and it often gets you a better rate too, since lenders see a bigger down payment as lower risk.
3. Increase EMI to Reduce Tenure
The idea to increase EMI to reduce tenure is underused, and it’s genuinely effective. Every time your income goes up, whether from an annual increment or a bonus, consider raising your EMI instead of keeping it fixed. Most lenders offer a reset window every couple of years where you can request this. The logic is simple: a higher EMI clears your principal faster, which means less interest accumulates over the remaining tenure. Someone who increases their EMI by even 10-15% whenever their salary rises can shave years off their loan and save substantially on interest, without feeling a heavier pinch, since the increase tracks their rising income.
4. Use Prepayments Strategically
A prepayment is a lump sum you put toward your loan outside your regular EMI, usually from a bonus, matured investment, or windfall gain. Early in your loan, most of your EMI goes toward interest rather than principal, so a prepayment made in the first few years has an outsized effect on reducing your total interest bill. Before making one, check with your lender on prepayment charges. Floating-rate loans in India generally don’t carry these charges, which makes prepayment even more attractive if your loan is on a floating rate.
Reduce Home Loan Interest Legally Through Negotiation and Balance Transfer
Here’s something most borrowers skip entirely: ‘Asking.’ If you’ve built a strong repayment history and your credit score has improved since you took the loan, you have real leverage to negotiate a lower rate with your existing lender. It costs nothing to ask, and lenders would often rather retain a reliable borrower at a slightly reduced rate than lose the account altogether.
If negotiation doesn’t work, a balance transfer is the next legitimate route. This means moving your outstanding loan to another lender offering a better rate. It’s one of the most reliable ways to reduce home loan interest legally, especially if your current lender’s rate has fallen out of step with the market. Just weigh the transfer costs, like processing fees, against the actual interest you’d save before switching.
How These Tactics Add Up to Meaningful Savings
Picture a loan of ₹50 lakh at an 8.5% interest rate with a 20-year tenure. Without any changes, your monthly EMI would be approximately ₹43,400, taking your total repayment to around ₹1.04 crore over the loan term. That means you’d pay roughly ₹54 lakh in interest alone.
Some of the most effective home loan interest saving tips include:
- Making a 25% down payment instead of 10%.
- Making a ₹2 lakh prepayment in the third year.
- Increasing your EMI by 10% every few years as your income grows.
Combined, these strategies can trim the total interest paid close to 20%, sometimes even more, depending on how early and consistently they’re applied. The earlier you act, the greater the compounding benefit.
How Partnering With BASIC Home Loan Can Help
Structuring a loan this well takes more than good intentions, it takes comparing offers, tracking rate changes, and knowing when a balance transfer actually makes sense. At BASIC Home Loan, we help you compare lenders side by side, so you can build a repayment plan around the best available terms instead of settling for whatever your first lender offers. We also provide expert guidance and every practical home loan interest saving tip to help you reduce your borrowing costs over the life of your loan.
So, if you’re planning to take a home loan and want a trusted partner by your side, BASIC Home Loan can help you secure the right loan, maximize your savings, and stay on track toward becoming debt-free sooner.