For many Non-Resident Indians (NRIs), owning a piece of their homeland is a dream. With India’s real estate market burgeoning, the prospect of buying property here has become increasingly attractive. But how does one navigate this path from thousands of miles away? This blog simplifies the process of obtaining NRI home loans, a vital step towards buying property in India.
Why India is an Attractive Market for NRIs
India’s real estate sector has seen exponential growth, offering lucrative investment opportunities. Factors like a booming economy, diverse property types, and sentimental value make India a top choice for NRIs. Furthermore, many NRIs view property in India as a secure asset for their retirement years or as a base for their families.
Suggested read: Buying a Second Home in India
Eligibility Criteria for NRI Home Loans
Before diving into the market, understanding the eligibility criteria for home loans is crucial. Generally, Indian banks consider age, employment status, and income stability. NRIs typically need to be employed for a certain period in the country of their residence and have a stable income source.
Required Documentation
The documentation process for NRIs is more stringent than for resident Indians. Key documents include passport and visa copies, overseas employment details, salary slips, and NRE/NRO bank account statements. Banks may also require a power of attorney, enabling a representative in India to handle transactions.
Types of Properties NRIs Can Invest In
NRIs are allowed to purchase almost all types of property in India except agricultural land, farmhouses, and plantation properties. Understanding this limitation is essential to avoid legal hurdles.
Suggested read: Home loan debt
Loan Features and Benefits
NRI home loans come with features like attractive interest rates, flexible tenure, and the option for a joint loan. The loan amount usually depends on the individual’s income and property value. Some banks also offer special benefits like online account management.
Tax Implications for NRIs
Investing in Indian real estate comes with its set of tax implications. NRIs must be aware of the income tax, capital gains tax, and rental income tax in India. There are also benefits under various sections of the Income Tax Act, which can be leveraged.
Repatriation of Funds
Understanding the repatriation rules is vital. The Reserve Bank of India allows NRIs to repatriate funds under certain conditions, which should be well understood to ensure compliance and ease of investment.
Choosing the Right Bank or Financial Institution
Selecting the right lender is as crucial as selecting the right property. Factors like interest rates, loan tenure, processing fees, and customer service play a significant role in this decision.
Suggested read: Home Loan Application Rejected
The Process of Applying for and Obtaining a Loan
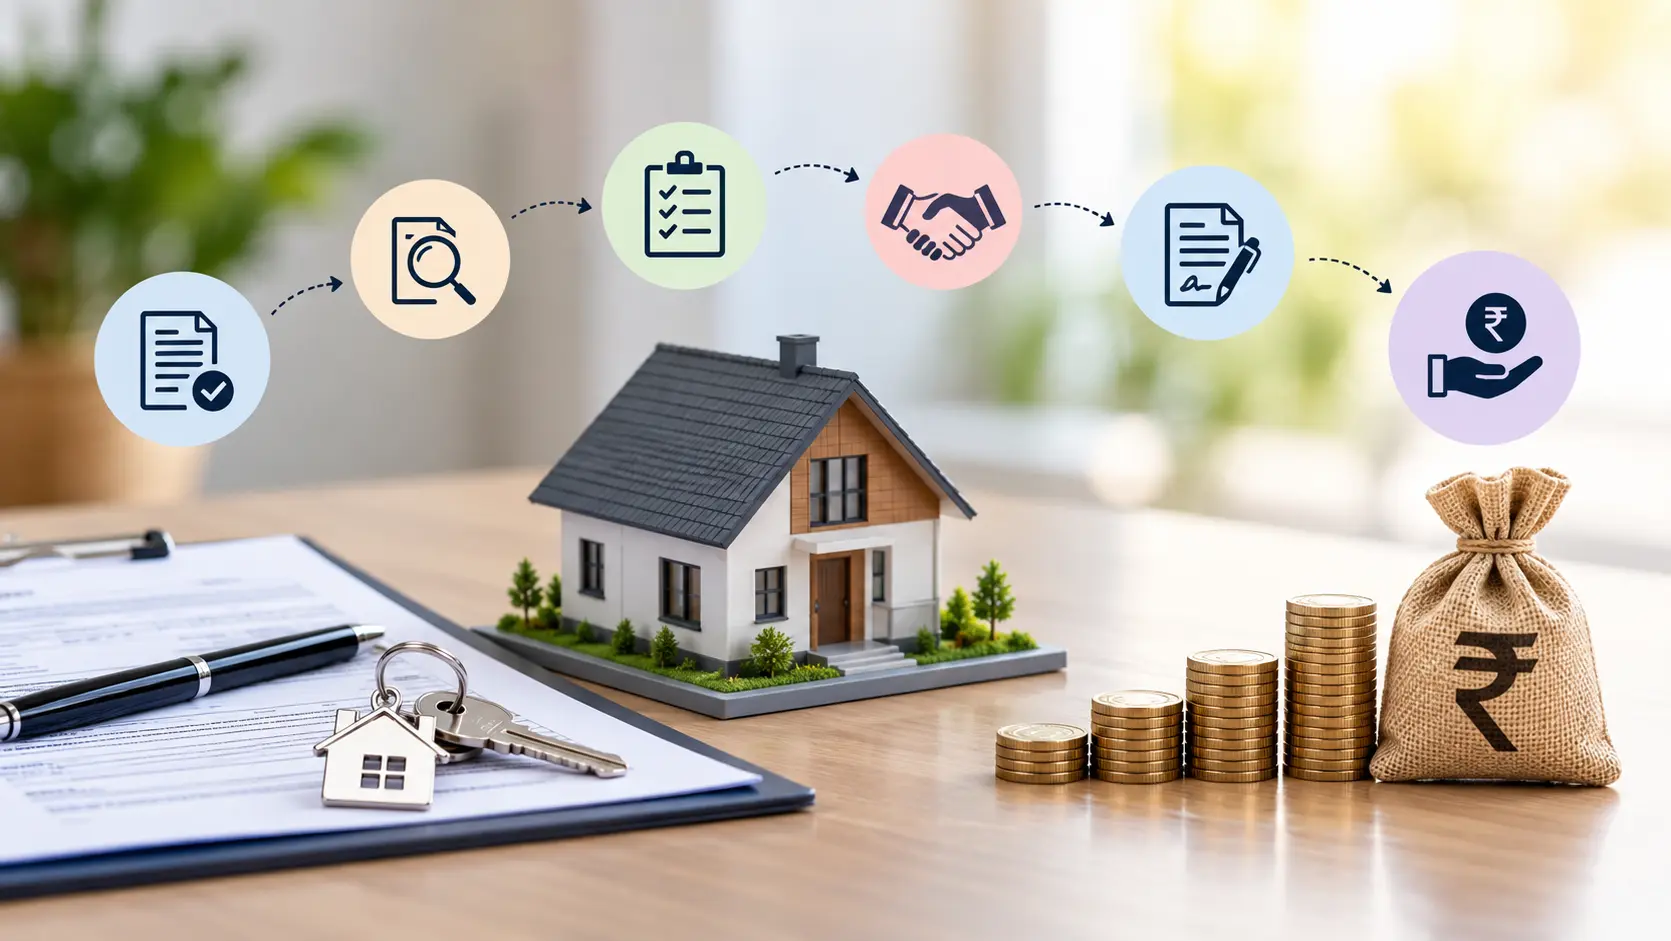
The loan application process involves submitting the application with requisite documents, property verification, loan sanction, and finally, the loan disbursement. It’s a structured process that demands attention to detail.
Legal Considerations and Due Diligence
Legal due diligence cannot be overstated. NRIs should ensure clear property titles, valid building permits, and a reputable builder. Seeking legal advice is often a wise step.
Buying property in India as an NRI is a significant financial and emotional decision. While the process might seem daunting, understanding the nuances of NRI home loans can simplify it. It’s advisable to do thorough research and consult financial and legal experts to make this journey smooth and fulfilling. With the right approach, owning a dream home in India is certainly within reach for the global Indian community.